
In 2022, the solar industry witnessed unprecedented growth, driven by policy support, technological advancements, and surging global demand. With 77 listed Chinese photovoltaic (PV) companies reporting a combined revenue of \$177 billion (¥1.26 trillion), the sector solidified its position as a cornerstone of the energy transition. At the heart of this transformation lies the critical role of solar inverters, which convert DC power from panels into grid-compatible AC electricity. This article explores the financial landscape, technological trends, and market dynamics shaping the PV industry.
Silicon Supply Chain: From Scarcity to Surplus
The polysilicon market experienced extreme volatility in 2022, with prices peaking at \$42.3/kg (¥303/kg) before halving by year-end. Major producers reaped extraordinary profits:
| Company | 2022 Revenue (Billion USD) | YoY Growth |
|---|---|---|
| Tongwei Co. | 203.5 | 119% |
| GCL Technology | 52.8 | 98% |
| Daquan Energy | 6.3 | 186% |
The polysilicon price trajectory followed a classic supply-demand model:
$$P(t) = P_0 \cdot e^{kt}$$
Where \( P_0 \) = Q1 2022 average price (\$33.1/kg), \( k \) = quarterly growth rate (0.35), until Q3 2022. Post-Q3, capacity expansions triggered price decay:
$$P(t) = P_{\text{max}} – \beta(t – t_{\text{peak}})$$
With \( \beta \) = 0.18 (weekly price decline coefficient).
Wafer Wars: Expansion Amid Margin Compression
Silicon wafer production surged 67% YoY to 357 GW, led by:
| Manufacturer | Capacity (GW) | Market Share |
|---|---|---|
| LONGi Green Energy | 150 | 28% |
| TCL Zhonghuan | 140 | 26% |
| Shuangliang | 40 | 7.5% |
The wafer thickness reduction race accelerated, with leading companies achieving:
$$t_{\text{wafer}} = 160 \mu m – 0.5 \mu m/\text{quarter}$$
Module Markets: Consolidation and Innovation
Top 4 module suppliers captured 65% of global shipments:
| Company | 2022 Shipments (GW) | YoY Growth |
|---|---|---|
| LONGi | 46.8 | 62% |
| JinkoSolar | 44.4 | 58% |
N-type TOPCon modules achieved 24.5% average efficiency:
$$\eta_{\text{TOPCon}} = \eta_{\text{PERC}} + \Delta \eta_{\text{passivation}}$$
Where \( \Delta \eta_{\text{passivation}} \) ≈ 1.2% absolute efficiency gain.
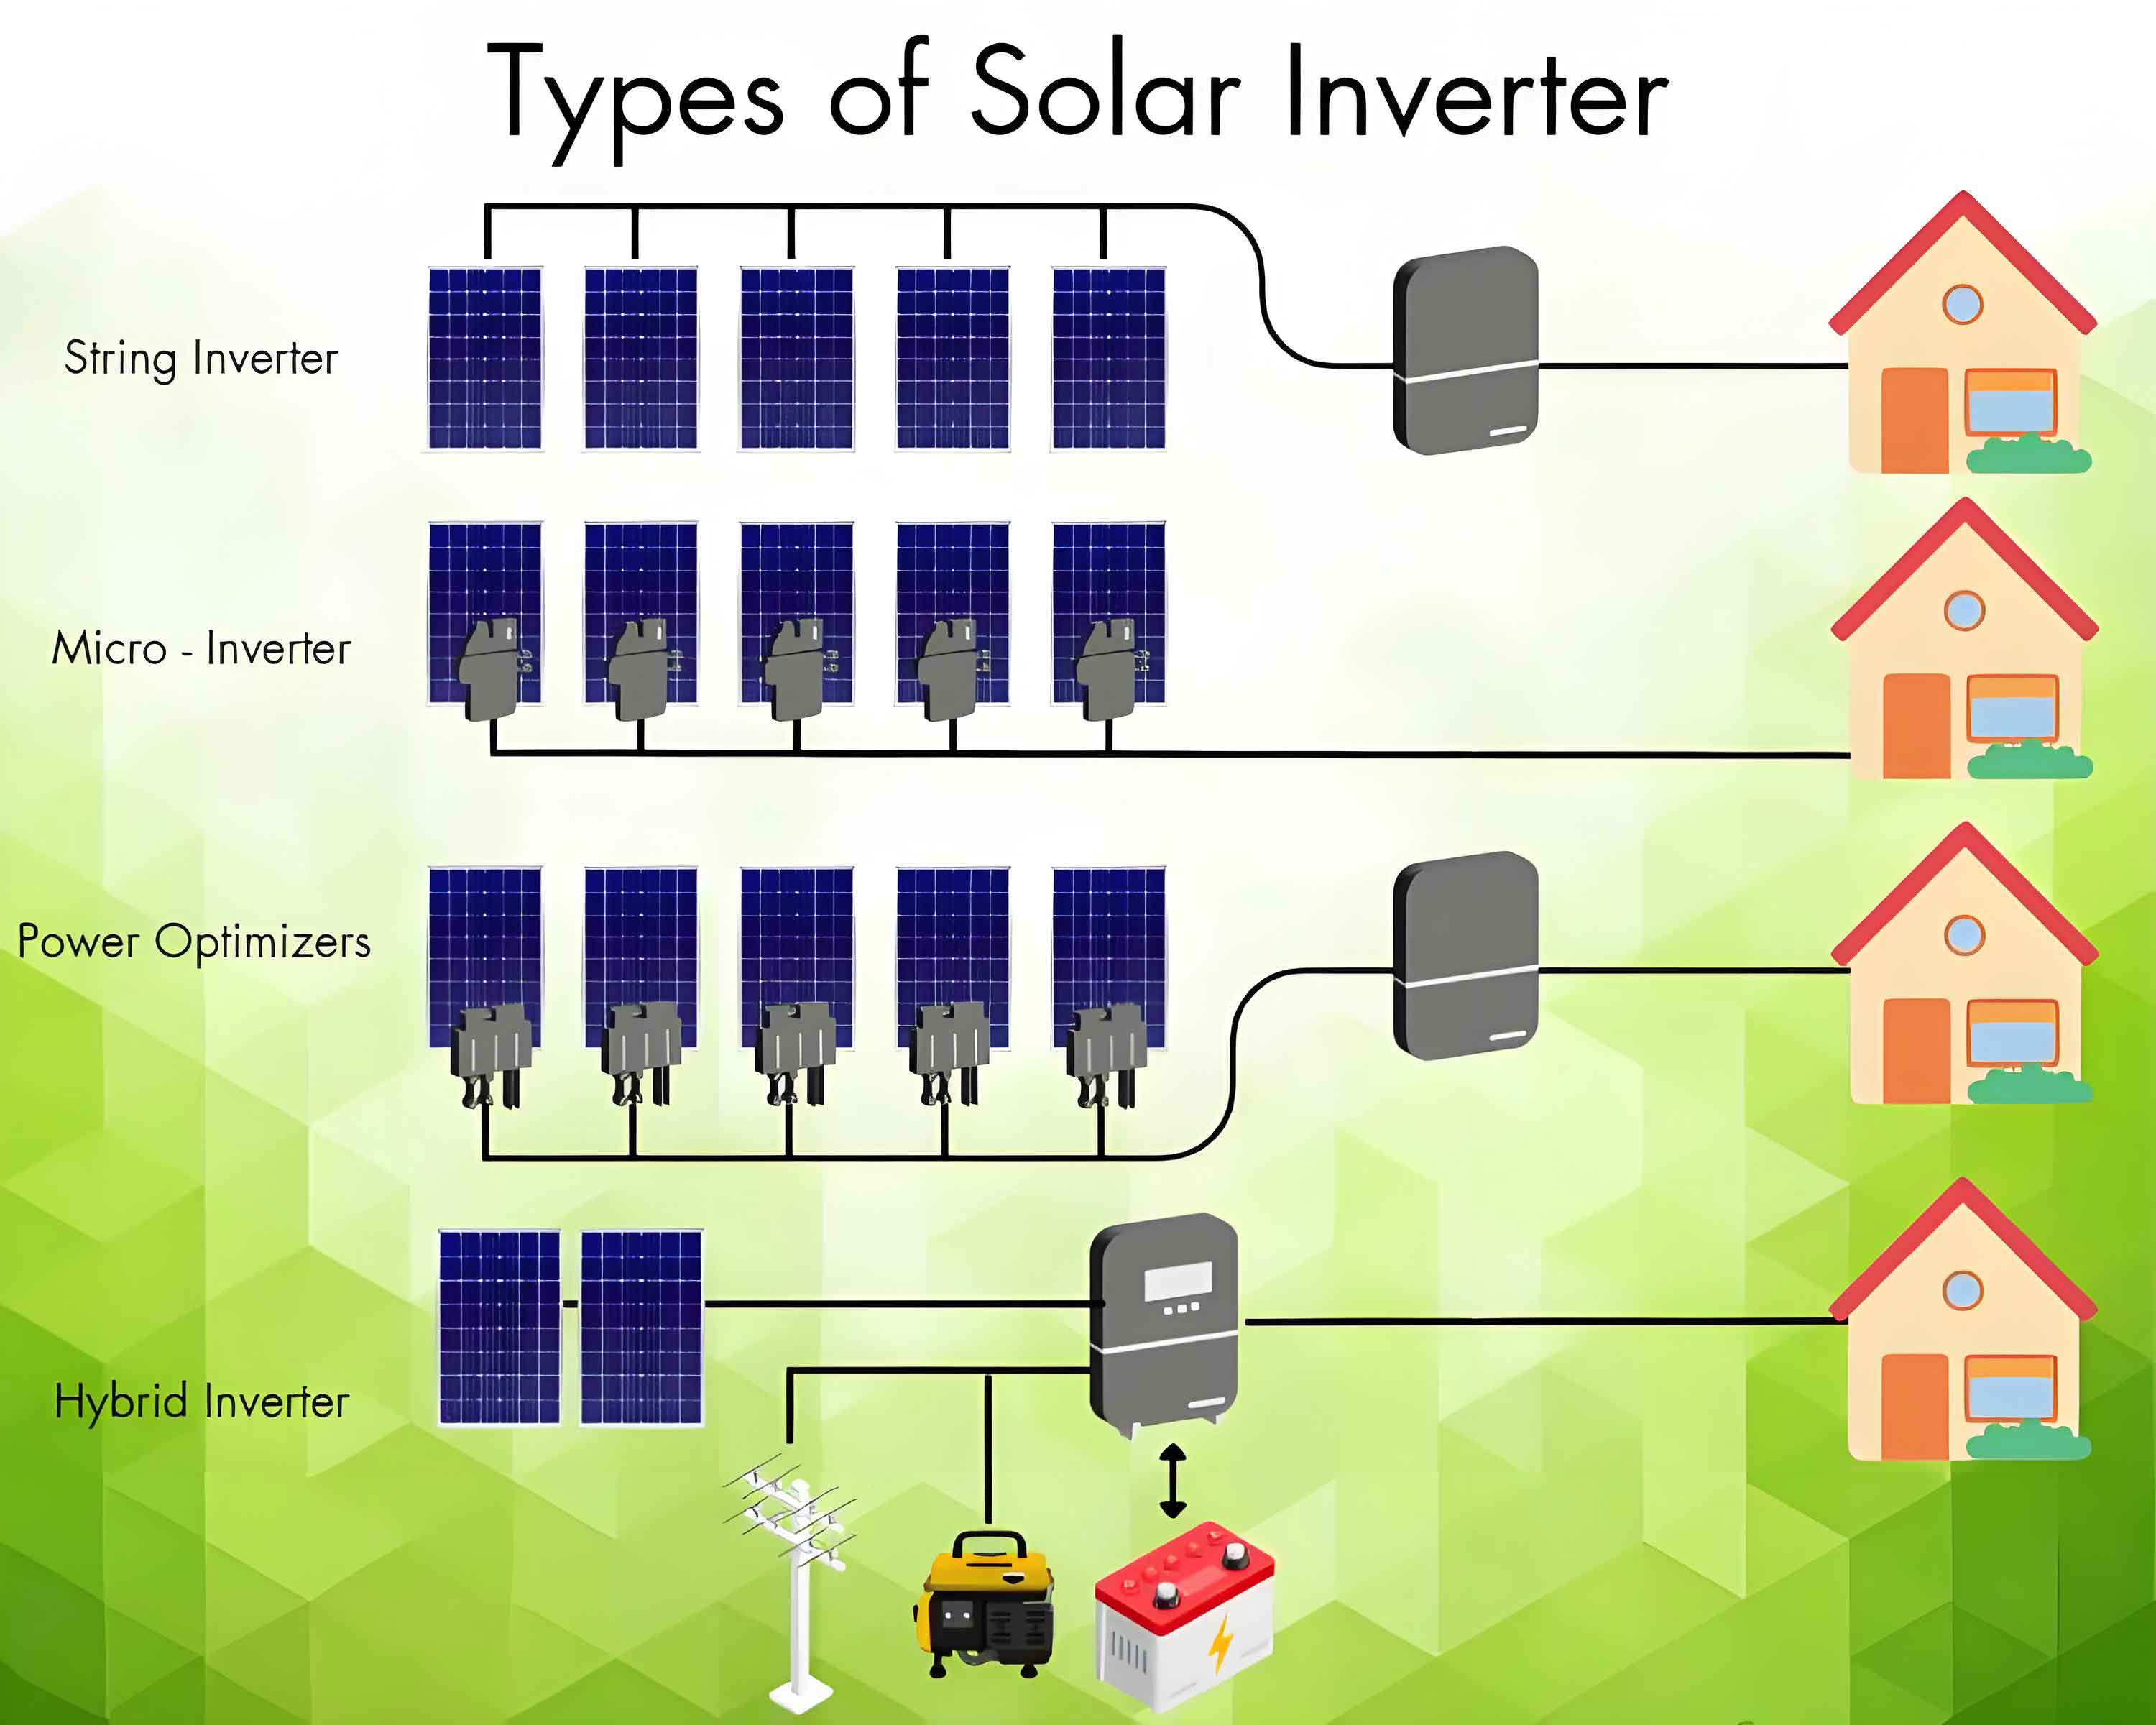
Solar Inverter Revolution: Efficiency and Intelligence
The solar inverter market grew 68% to \$18.9 billion, driven by:
| Technology | 2022 Efficiency | 2030 Projection |
|---|---|---|
| String Inverters | 98.5% | 99.2% |
| Microinverters | 96.8% | 97.9% |
Advanced solar inverters now incorporate AI-driven grid support functions:
$$Q_{\text{reactive}} = \sqrt{S^2 – P^2}$$
Where \( S \) = apparent power, \( P \) = active power. Leading suppliers like Sungrow and Huawei deployed neural networks for real-time grid impedance adaptation:
$$Z_{\text{grid}} = \frac{V_{\text{thd}}}{I_{\text{thd}}} \cdot e^{j\theta}$$
Enabling 30% faster fault ride-through compared to conventional designs.
Market Projections and Challenges
The global PV market is projected to grow at 22% CAGR through 2030, with solar inverters requiring:
- 1500V system compatibility
- ≥ 99% CEC efficiency
- Cybersecurity certifications (IEC 62443)
Emerging challenges include:
$$LCOE_{\text{storage}} = \frac{C_{\text{cap}} + \sum \frac{O\&M}{(1+r)^t}}{\sum \frac{E_{\text{dis}}}{(1+r)^t}}$$
Where battery integration becomes critical for solar inverter systems as penetration exceeds 25% in many grids.
With technological breakthroughs and manufacturing scale, the PV industry – particularly advanced solar inverter solutions – will remain central to achieving global decarbonization targets. The next decade will witness the rise of 99%+ efficiency hybrid inverters, AI-optimized grid interfaces, and terawatt-scale deployment.